Insurance Automation: From Underwriting to Claims
The insurance industry is undergoing fundamental transformation driven by automation and AI. Underwriting automation uses machine learning to assess risk from structured and unstructured data — satellite imagery, IoT sensors, telematics, and wearable devices enable more accurate risk assessment and personalized pricing.
Claims processing automation extends from first notice of loss through settlement. AI triage systems classify claims by complexity and route simple claims for straight-through processing. Computer vision analyzes damage photos to estimate repair costs. Intelligent document processing extracts data from policy applications, medical records, and repair estimates using OCR and NLP. Fraud detection models analyze claim patterns across the entire portfolio, identifying fraudulent networks that human investigators would miss.
Underwriting: more signal, same accountability
ML on structured application data plus imagery, telematics, and documents can price more tightly. Someone still owns the decision. Log features, version the model, and keep a referral path for exceptions. Personalized pricing without fair-lending review is a lawsuit with extra steps.
Claims: FNOL to settlement
Triage by complexity, straight-through on the boring ones, computer vision on damage photos, and document extraction on medical and repair packets. Human adjusters should spend time on ambiguity and customer harm, not re-keying.
Fraud as a network problem
Graph features across claimants, shops, and providers beat a single-claim rules engine. False positives destroy NPS; tune with investigators, not only precision dashboards.
Where MCP and agents actually fit
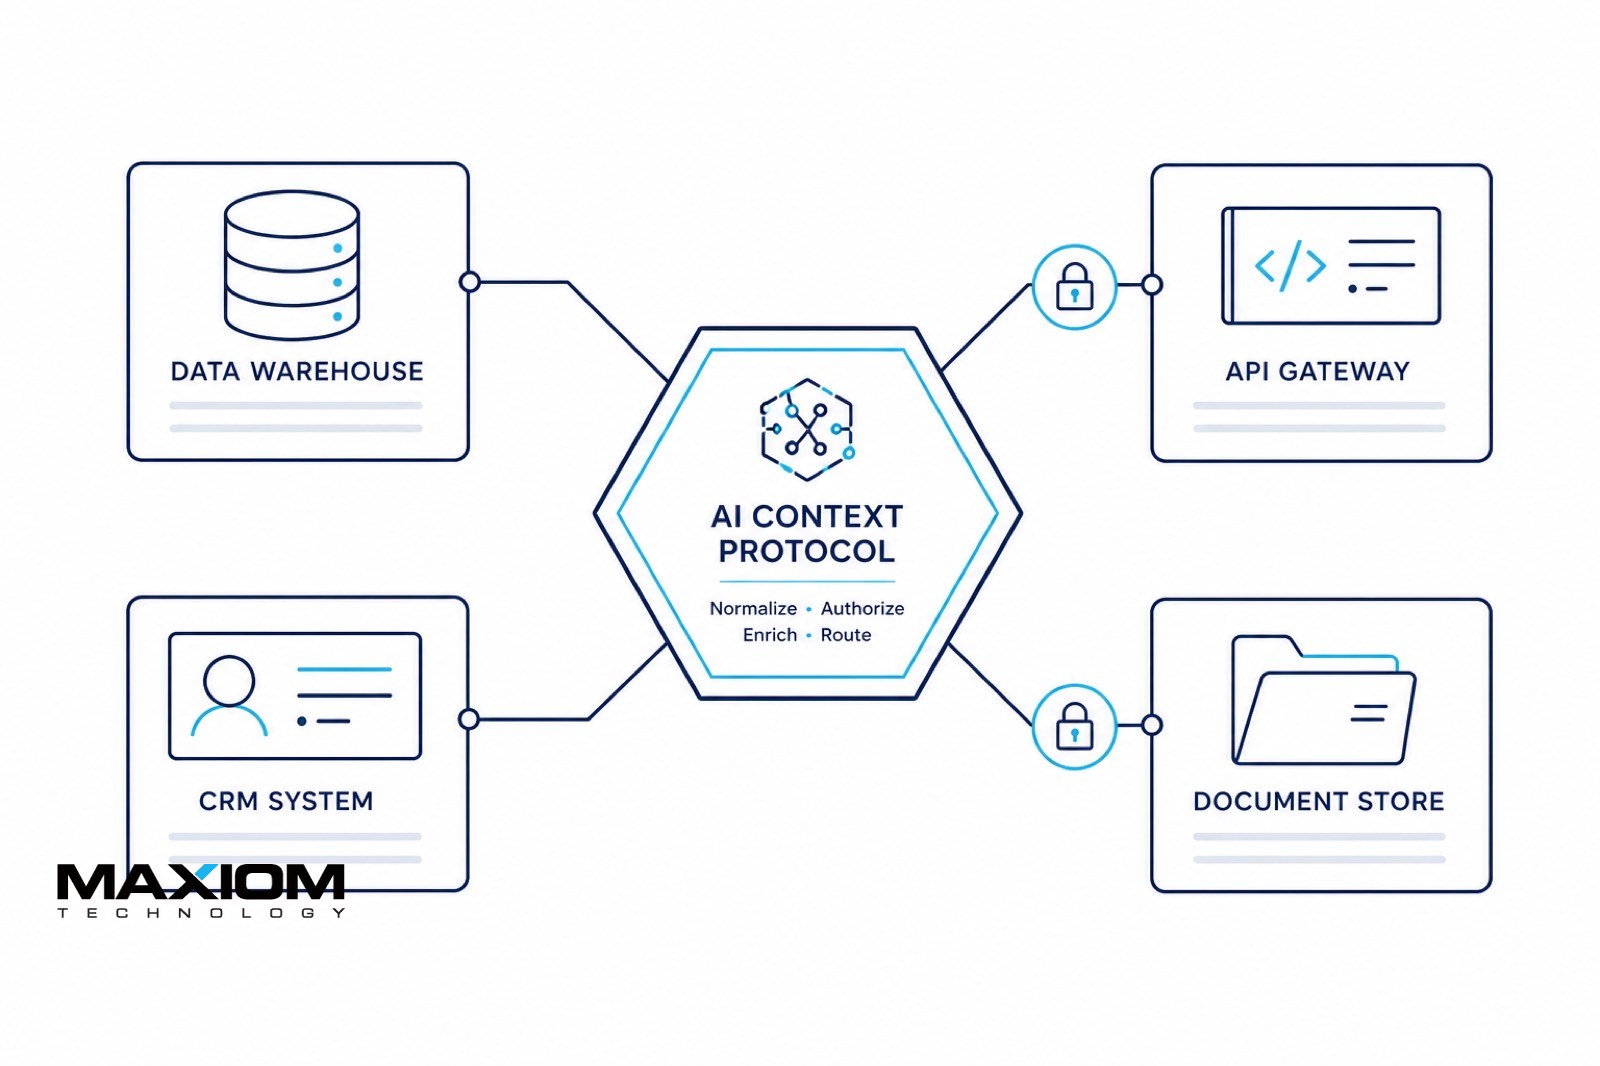
If you want an assistant over policy admin, it needs audited tool access — not a paste of PII into a public chatbot. That is custom integration work, not a plugin.
How to sequence the program
Pick one product line and one journey (quote or FNOL). Prove cycle-time and leakage. Then expand. Machine learning services and a written scoping call beat a multi-year “insurtech transformation” brand.
FAQ
Will automation replace adjusters?
It replaces re-keying. Complex claims, cat events, and bad-faith risk still need experienced humans.
What about healthcare-adjacent policies?
If PHI is in scope, treat it as healthcare engineering — Maxiom Labs is the sister practice for that constraint set.